Treasury Issuance and Bear Steepening: Equities Hold Ground
Are rising Treasury yields forcing an equity market rebalancing?
While the climb in long-term borrowing costs increases discount rates and compresses the equity risk premium, it has not triggered a broad institutional flight into defensive sectors. Equities have largely absorbed higher yields, and expected portfolio reallocations have not appeared in trading data.
The 2024 yield rebound
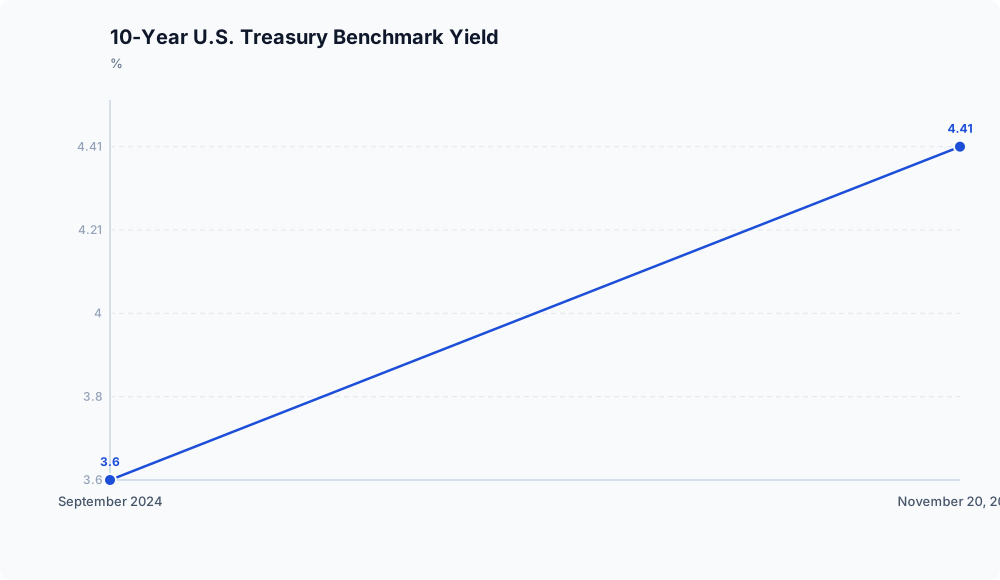
The benchmark 10-year U.S. Treasury yield rose from a low near 3.6% in September to roughly 4.41% by November 20, 2024, according to reporting by CNBC. That increase of roughly 80 basis points over two months pushed borrowing costs toward levels investors watch as potential headwinds for risk assets.
Market analysts cited by CNBC attributed the rise to changing growth forecasts and fiscal expectations after the U.S. presidential election. Wolfe Research strategist Chris Senyek noted that expectations of a future budget reconciliation bill covering various spending priorities could keep upward pressure on long-term rates. UBS Global Wealth Management also pointed to expectations of firmer economic growth and modestly higher inflation.
Market commentary often links this yield curve steepening to heavy federal debt sales and deficit concerns. However, data on Treasury auction sizes, supply absorption, or deficit expansion is not included in the source reports. While fiscal expectations and post-election legislative priorities are cited as drivers by CNBC, the reporting does not verify how much debt issuance volumes contributed to the move from 3.6% to 4.41%.
Discount rates and the equity risk premium
When long-term risk-free rates rise, the discount rates applied to projected corporate cash flows climb as well. Growth equities derive a large share of their valuation from cash flows expected years ahead, so higher yields reduce the present value of those future earnings.
This rise in yields also narrows the equity risk premium (ERP), the excess return investors demand over risk-free assets to hold stocks. When yields advance while stock prices hold steady, that return cushion shrinks.
This narrow spread contrasts with earlier market crises. Aswath Damodaran’s implied U.S. ERP series rose above 6% to 7% during the 2008 financial crisis, as documented by Stock Alarm. During periods when implied ERPs exceeded 6% to 7%, lower equity multiples provided a valuation buffer for investors.
With 10-year yields holding above 4%, stocks lack that historical margin. Unless corporate earnings grow fast enough to offset higher discount rates, these yield levels place a cap on valuation multiples.
Has institutional rotation occurred?
Standard asset allocation models suggest that higher discount rates should prompt institutions to shift money out of high-multiple, rate-sensitive growth stocks and into defensive sectors with steady dividends and predictable near-term earnings.
Market data does not show that rotation taking place. As reported by CNBC, major stock indexes were little changed even as the 10-year yield reached 4.41% on November 20, 2024. Equities absorbed the rise from the September low of 3.6% without broad selling. Without sector-level flow data, there is no proof that yields approaching 4.50% have caused an active rotation into defensive equities.
Valuation outlook
The late-2024 rise in Treasury yields compresses valuation multiples, but equity prices have held up without broad declines or visible defensive rebalancing. As long as yields stay elevated, equity valuations depend on earnings growth to justify current prices against higher risk-free returns.
Disclaimer: This analysis is for informational purposes only and does not constitute investment, financial, real estate, or legal advice. Always consult a licensed financial advisor before making investment decisions.